The First Blast Heard Across the Iron Range: Inside TMCR's Minnesota Royalty Play
The Metals Royalty Company (TMCR) just fired the first production blast at its Mesabi Metallics iron ore royalty asset — 211,000 tons of ore fractured in Minnesota's first new mine in 50 years. With a 2% gross overriding royalty on a $2.5 billion DR-grade pellet project, a $363M market cap, and a Diamond Equity price target of $20.35, TMCR is a micro-cap royalty play at the exact moment American iron ore is coming back.
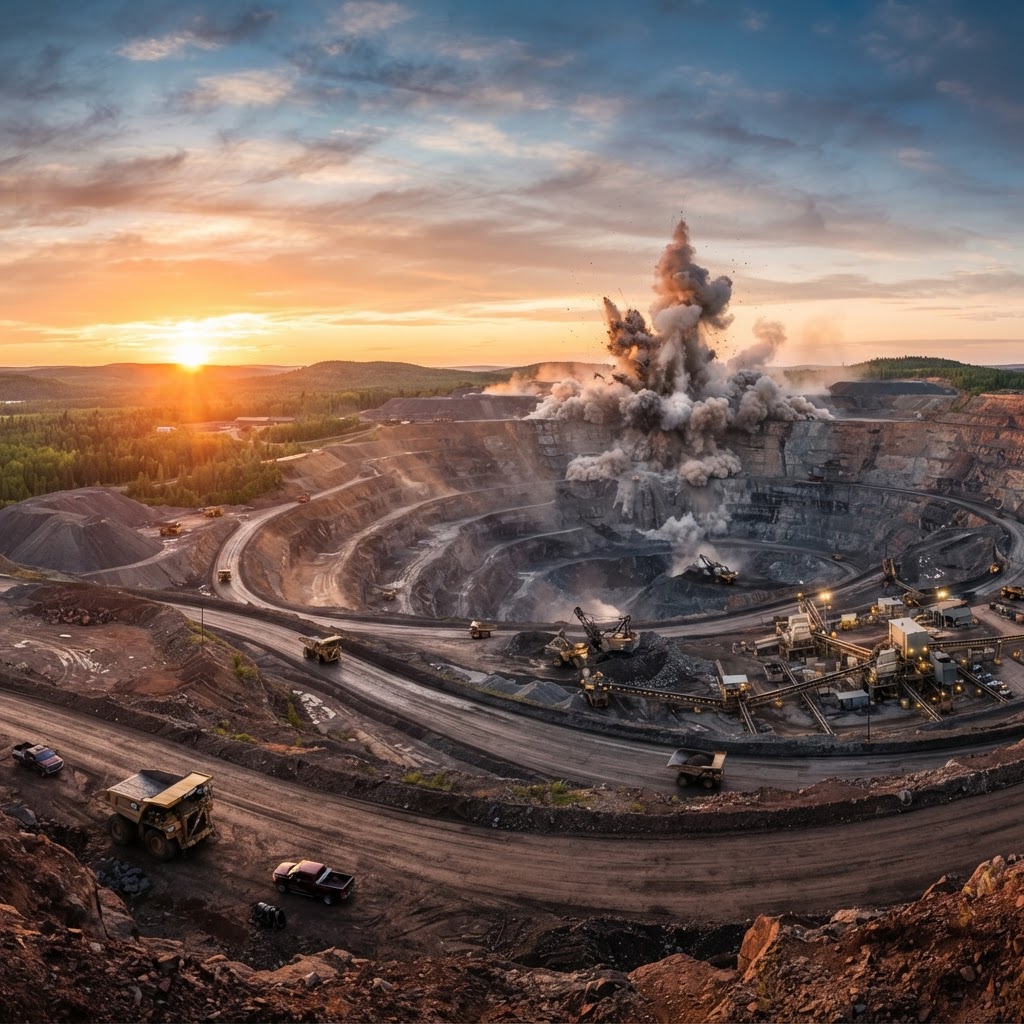
The First Blast Heard Across the Iron Range
On July 10, 2026, a 66-hole blast pattern fractured approximately 211,000 tons of iron ore at the Mesabi Metallics project near Nashwauk, Minnesota. It was the first production blast at what is the first new American mine and pellet plant in 50 years. The shockwave traveled further than the Iron Range — it marked the de-risking moment for a micro-cap royalty company that has been quietly assembling one of the most contrarian bets in North American metals.
That company is The Metals Royalty Company (NASDAQ: TMCR), and it holds a 2% gross overriding royalty on the entire Mesabi Metallics output. At a market cap of roughly $363 million, TMCR is a single-asset royalty play sitting on top of a $2.5 billion iron ore project at the exact moment American domestic mineral production is being rebranded as a national security imperative.
The Asset: Mesabi Metallics and the "Patriot Pellet"
Mesabi Metallics is not a speculative exploration target. It is a fully permitted, under-construction, direct-reduction (DR) grade iron ore pellet plant — the kind of asset that produces the high-purity feedstock needed for electric arc furnaces and green steel production. The project is designed to produce 7 million metric tons of DR-grade pellets per year, branded as "Patriot Pellet," and has been wrapping up construction through 2026 with round-the-clock mining operations expected to begin in mid-July.
The timing is not accidental. DR-grade iron ore is the feedstock for decarbonized steelmaking, and the United States produces almost none of it domestically. Every ton that Mesabi produces displaces imports from Brazil, Ukraine, or West Africa. In a market where steelmakers are increasingly pressured to clean up their supply chains, a domestic DR-grade pellet is both an industrial and a political asset.
The first blast confirms the mine is transitioning from construction to production. Mesabi expects weekly blasting to continue as it ramps toward full-scale operations, with the pellet plant expected to come online in Q3 2026.
The Royalty: What TMCR Actually Owns
TMCR's entire investment thesis rests on a 2% gross overriding royalty (GOR) on Mesabi Metallics' iron ore production. The company closed the royalty acquisition for $132.5 million and subsequently exercised an option to acquire an additional 1% royalty interest, bringing its total exposure to 2% of gross production revenue.
The beauty of a gross overriding royalty is its simplicity. TMCR does not pay for mining costs, pellet plant capex, labor, equipment, or any operating expense. It collects a percentage of top-line revenue — the moment ore moves and pellets sell. This is the same business model that built Franco-Nevada and Wheaton Precious Metals, but applied to iron ore and at a fraction of the size.
Here is the rough math: at 7 million metric tons of annual production and a conservative DR-grade pellet price of $120 per ton, Mesabi's gross revenue would approach $840 million annually. TMCR's 2% royalty would generate approximately $16.8 million per year in passive royalty income. If pellet prices run hotter — and DR-grade premiums have been widening — that figure scales linearly with zero additional capital expenditure from TMCR.
Against a $363 million market cap, that implies a royalty yield of roughly 4.6% at full production — a number that would expand materially as Mesabi ramps to nameplate capacity and if iron ore prices cooperate.
The Parent: TMC's Deep-Sea Mining Connection
TMCR is not an orphan. It was spun out of TMC The Metals Company (NASDAQ: TMC), the Vancouver-based deep-sea mining pioneer. TMC retains a 22.44% stake in TMCR (approximately 13.9 million shares as of June 2026), and the two companies share leadership — Gerard Barron serves as Chairman & CEO of TMC and Director of TMCR.
The relationship cuts both ways. On one hand, TMCR benefits from TMC's deep institutional knowledge of critical minerals, regulatory navigation, and capital markets experience. On the other hand, TMC's deep-sea mining ambitions remain politically controversial and unproven at scale, and the affiliation means TMCR's story is sometimes tangled with a risk profile it does not directly carry. Investors evaluating TMCR need to separate the royalty company's clean cash-flow thesis from the parent's more speculative seafloor mining narrative.
Financials: Cash, Burn, and the Yorkville Backstop
As of March 31, 2026, TMCR held $31.3 million in cash with $32.0 million in working capital. The Q1 2026 net loss was $20.6 million — not from operations (which are minimal for a royalty company) but largely from non-cash items, financing costs, and the ramp-up of its royalty acquisition. Operating expenses were a negligible $241,000, reflecting the lean structure of a royalty holder.
The company has also secured a funding facility with Yorkville Advisors Global LP for up to $125 million, providing a capital backstop as it awaits first royalty revenue. The question is whether $31.3 million in cash plus the Yorkville facility is enough runway to bridge the gap between the first blast (July 2026) and first pellet sales (Q3 2026 and beyond). If Mesabi's timeline holds, the gap is measured in weeks, not quarters.
The Bull Case
The thesis is straightforward: TMCR is a micro-cap royalty company with a clean 2% GOR on a $2.5 billion asset that just fired its first production blast. The pellet plant is fully permitted, under construction, and designed to produce 7 million tons per year of a product — DR-grade iron ore — that is in structural deficit in the United States. Diamond Equity Research initiated coverage with a $20.35 price target against a current price of $5.85, implying roughly 3.5x upside. The "Patriot Pellet" branding and the political tailwind of domestic critical mineral production add a narrative catalyst that could drive re-rating as production volumes become visible.
The Bear Case
The risks are equally clear. TMCR is a single-asset royalty company with zero current revenue. The stock has lost approximately 60% since its April 2026 Nasdaq direct listing at $21.38, reflecting investor impatience and dilution concerns. The $132.5 million royalty acquisition was funded in part through share issuance, and the Yorkville facility is equity-linked — meaning additional dilution is possible. If Mesabi's pellet plant timeline slips, or if iron ore prices decline, TMCR's royalty cash flow could arrive later and smaller than expected. And at $31.3 million in cash against ongoing corporate and financing costs, the runway is not infinite.
There is also concentration risk. TMCR's entire portfolio is one royalty on one project. If Mesabi fails, TMCR fails. There is no geographic or commodity diversification to fall back on.
Scoring and Quadrant Classification
Asset Quality / Execution (Signal Score): 8.5/10 — The first production blast is a tangible, verifiable operational milestone. Mesabi is fully permitted, under construction, and backed by a $2.5 billion project scope. TMCR's royalty structure is clean (GOR, no operating costs), and Diamond Equity Research provides institutional coverage. The $31.3M cash position is adequate for the short bridge to first revenue. The TMC parentage adds credibility but also complexity.
Promotion Intensity (Hype Score): 7/10 — The "Patriot Pellet" branding, RedChip investor webinar, and regular press release cadence indicate an active IR program. However, the promotion is backed by genuine operational milestones (first blast, construction progress, permit status), not just narrative. The 60% post-listing decline suggests the market is currently skeptical, which paradoxically reduces the hype premium.
Quadrant Label: Market Leader / Catalyst Play — High asset quality combined with active promotion. This is a company with a real asset, a real milestone, and an active narrative — positioned for a re-rating if production volumes materialize on schedule.
The Bottom Line
TMCR is a binary bet on one question: can Mesabi Metallics convert a first blast into steady pellet production on time? If yes, TMCR becomes a cash-flowing royalty company at a fraction of the valuation of its larger peers, with a domestic critical minerals narrative that aligns with federal policy. If no, the single-asset structure, the cash burn, and the dilution overhang will pressure the stock further.
For micro-cap investors who understand the royalty model and can tolerate single-asset risk, the first blast at Mesabi is the kind of de-risking event that separates a story from a speculation. The next test is Q3 2026, when the pellet plant is expected to come online and the first royalty checks could start flowing.
Todd Colpron is the Managing Partner of Eliakim Capital, a private investment and strategic advisory firm that manages its own capital while working alongside select family offices and private investors to identify and support exceptional opportunities.
Important Disclosure and Disclaimer
This publication is provided solely for general educational and informational purposes. Nothing contained in this publication constitutes, or should be construed as, investment, financial, legal, accounting, or tax advice; a recommendation or endorsement of any security, issuer, transaction, or investment strategy; or personalized advice based on any reader's particular financial circumstances.
This publication does not constitute an offer to sell, a solicitation of an offer to buy, or an invitation to enter into any transaction involving securities. Any offer or sale of securities may be made only through applicable offering documents and in accordance with applicable federal and state securities laws.
The Daily MicroCap and Eliakim Capital are not registered broker-dealers and do not execute securities transactions, accept investor funds, or provide brokerage services. Unless separately and expressly disclosed, neither The Daily MicroCap nor Eliakim Capital is acting as an investment adviser to any reader, and no advisory, fiduciary, attorney-client, or other professional relationship is created by this publication.
Information contained herein may be obtained from issuers, public filings, press releases, third-party sources, or other materials believed to be reliable; however, its accuracy, completeness, timeliness, and reliability are not guaranteed, and the information may not have been independently verified. Opinions and estimates are made as of the publication date and may change without notice.
Any statements regarding anticipated events, business prospects, financial performance, valuation, market opportunities, or future results are forward-looking and inherently uncertain. Actual outcomes may differ materially due to known and unknown risks.
Microcap and emerging-company securities can be highly speculative, volatile, illiquid, and subject to substantial dilution, limited publicly available information, and the risk of a complete loss of invested capital. Readers must conduct their own independent investigation and consult appropriately licensed financial, legal, and tax professionals before making any investment decision.
Neither The Daily MicroCap nor Eliakim Capital received compensation from the issuer for preparing or distributing this article.
Past performance is not indicative of future results. No representation or warranty is made regarding any investment outcome.